← Reverse mortgages in Michigan
Can equity in your Kalamazoo home become spendable, tax-free money? In most cases, yes. Reverse mortgage draws are loan proceeds rather than income, so they are generally tax-free, and a HECM line of credit grows on the unused portion over time. On a $230K Kalamazoo home in Kalamazoo County, you can open that line now and pull from it on your own timeline down the road.
A typical Kalamazoo home is worth around $230K, and for a longtime owner it is usually paid off with real equity behind it. A reverse mortgage only fits some situations, and I will say so when it does not. See how Kalamazoo compares on my Michigan aging-in-place overview.
Updated
On this page
- Local reverse mortgage broker in Kalamazoo
- Aging in place in Kalamazoo
- What is my Kalamazoo home worth?
- Reverse mortgage calculator
- Cost of aging in place
- Is a reverse mortgage right for me?
- Learn how reverse mortgages work
- Reverse mortgage options in Kalamazoo
- How much a reverse mortgage costs in Kalamazoo
- Condos and HOA
- Reverse mortgage FAQs
Reverse Mortgage Specialist in Kalamazoo, MI
Who is a local reverse mortgage broker in Kalamazoo, MI? Christopher Gibson (NMLS #1910430) is an independent broker with C2 Financial Corporation (NMLS #135622). He helps Kalamazoo homeowners age 55 and older (age 62+ for the government-insured HECM) turn home equity into funds for retirement. Because the funds are loan proceeds rather than income, they are generally not subject to federal income tax.* Call or text 720-449-6622.
Aging in place in Kalamazoo, at a glance
The pros and cons, every measure I track, sorted by which way it cuts. Full detail below.
| Works in your favor | Neutral or mixed | Plan around it |
|---|---|---|
|
|
|
Figures: U.S. Census ACS 2020-2024 5-Year; County Health Rankings 2025 (life expectancy, county level); NOAA 1991-2020 Climate Normals; FEMA National Risk Index (per hazard, not the composite). This product uses the Census Bureau Data API but is not endorsed or certified by the Census Bureau.
Why a reverse mortgage appeals to Kalamazoo homeowners 55+ attempting to age in place
Kalamazoo pairs Western Michigan University with a strong medical and brewing scene. Homes bought decades ago now run around $230K and are usually mortgage-free, and that paid-off equity is real money on a fixed income. A reverse mortgage turns some of it into cash flow while you stay in the home.
Kalamazoo combines a major university and medical presence with affordable, historic neighborhoods where many retirees have owned homes for decades. Values are modest by state standards, but longtime owners often hold most of their home free and clear, giving them meaningful equity to draw on against fixed incomes. A HECM can supplement Social Security, cover healthcare, or fund repairs on older housing stock while owners remain in familiar city neighborhoods.
Kalamazoo reverse mortgage facts and figures
Kalamazoo is affordable by Michigan standards, and that affordability is exactly what lets home equity stretch a fixed income here. Here are a few numbers worth knowing:
Home values: Zillow, mid-2026. HECM limit: HUD/FHA 2026. Property tax: U.S. Census. Figures change, so ask me for today’s numbers on your home.
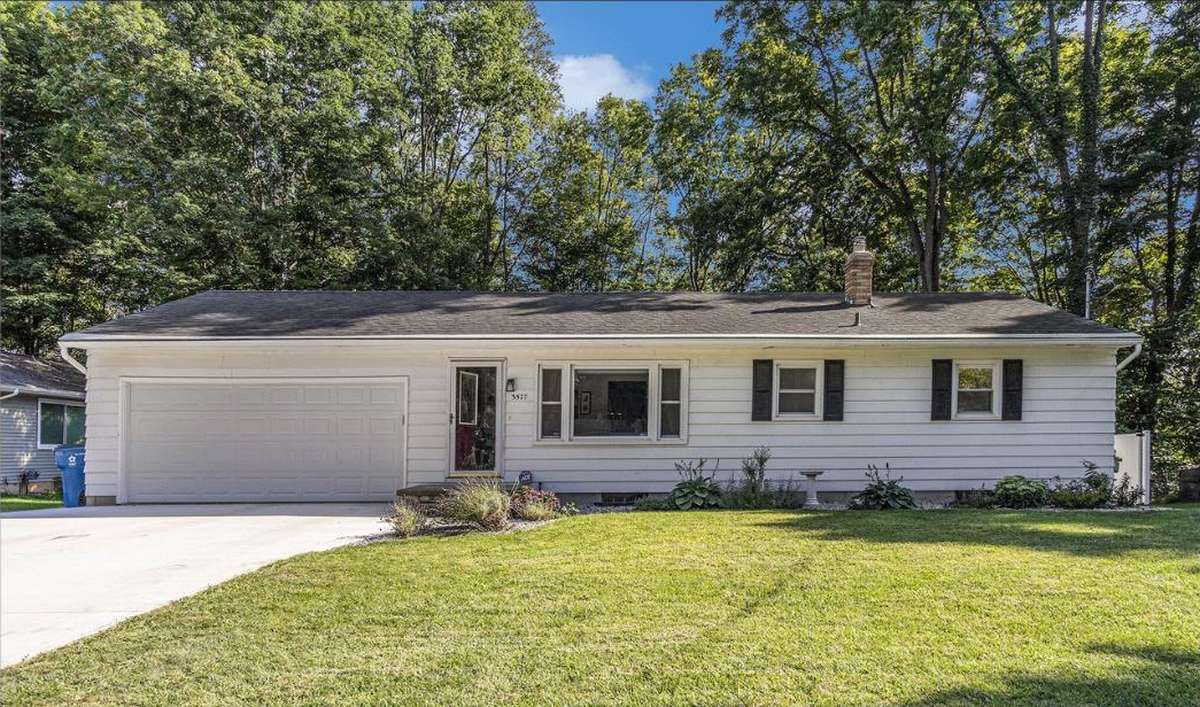
What is your Kalamazoo home worth today?
Curious what your home could be worth, and how much equity you have to work with? Use my free home-value tool below. Enter your address for an instant Kalamazoo estimate you can track over time, at no cost and no obligation.
Reverse mortgage options in Kalamazoo: HECM vs. jumbo
Most homes here are covered by the government-insured HECM, while higher-value homes and many condos fit a proprietary jumbo. For the full side-by-side of HECM, jumbo, HELOC, and HEI, see the reverse mortgage comparison table, or the types of reverse mortgages for a plain-English rundown.
For a full side-by-side of every program and how to choose, see the types of reverse mortgages.
Buying a home? Consider a HECM for Purchase (H4P)
A HECM for Purchase lets you buy your next home using a reverse mortgage, so you put down a portion and finance the rest with no required monthly principal-and-interest payment. For a Kalamazoo owner trading an older two-story for a single-level place, it is a clean way to move without taking on a new monthly payment.
How much you can access depends on age, rates, and value. Start your own estimate with the reverse mortgage calculator below.
Reverse Mortgage Calculator
Let’s calculate how much equity you can unlock.
A reverse mortgage is a loan. The balance grows over time and is repaid when the last borrower leaves the home. You keep the title, and you remain responsible for property taxes, homeowners insurance, and upkeep.
Aging in place in Kalamazoo with a reverse mortgage: what it really costs
I would rather show you the Kalamazoo numbers than describe the product again. All figures are published ones. Where none exists I say that plainly.
The FHA appraisal, and what a 1959 house triggers
Housing here dates to a median of 1959, older than the Michigan median of 1972 and older than most of the state. About 76% of the housing here went up before 1980, which is the line that matters for lead paint. The FHA appraisal behind a HECM is really a habitability inspection with a number attached. What gets written up is predictable: the roof, the furnace, the water heater, the wiring, and lead paint on the older stock. None of that kills a file. It goes into a repair set-aside funded from your proceeds, capped at 15% of the maximum claim amount.
How much of a Kalamazoo retirement the house consumes
Median monthly cost to keep a Kalamazoo house with no mortgage on it: $623. It covers the tax bill, the insurance, the utilities and the fuel. Against a typical 65-and-over household income of $55,160, that is 14% of everything coming in. Across Kalamazoo, 21% of owners 65 and over already spend 30% or more of income on the house. The payment goes. The bill stays. That distinction is the single most important thing to understand before signing.
What happens when it is serious
The in-town hospital is Bronson Methodist Hospital, a Level I trauma center, part of Bronson Healthcare. Put a number on it. Bronson Methodist Hospital, Level I, is 1.2 miles from the middle of town, and the nearest Level I is 1.2 miles. Worth a conversation with the family before it becomes an urgent one.
A winter obligation with a clock on it
Kalamazoo gets 19 days a year with at least an inch of snow down. You are required to clear the adjoining public walk, and there is a clock on it: 48 hours, cleared to bare pavement across the full width and treated. Enforcement runs to the city removes it at about 15 cents a foot plus a $30 administrative fee and assesses it as a lien; putting snow into the street is a separate $100 infraction. That is Kalamazoo Code 33-18. Worth pricing a service before you need one. The winter you cannot do it yourself is rarely the winter you planned for.
How people here get around later on
The local option is Kalamazoo Metro Connect, curb to curb across the county, open to the reduced fare starts at 62 with a certification form. Expect to pay $4.00 reduced, against a $12.00 regular cash fare. Sign up early. Most require an application and a few days’ notice per trip, which is fine when you plan and useless when you do not.
Where Michigan differs from the other states I lend in
Every Michigan borrower asks about Proposal A. The answer is that establishing a security interest is expressly not a transfer of ownership under MCL 211.27a(7)(j), so your taxable value stays capped. More, including the Homestead credit, on the Michigan page.
Before you borrow for it, check what the millage covers
The Kalamazoo County Area Agency on Aging, Region IIIA levies a dedicated senior services millage, 0.3462 mill through 2029, renewed in August 2024 and raising about $3.7 million a year. It covers 45 separate services for residents 60 and older and their caregivers, from home-delivered meals to help with bathing and housecleaning. I tell people to work through the local programs before we size a loan. Anything they cover comes off the number you need.
What the federal numbers say about aging in place here
The BEA puts local prices at 95 where the US is 100, across the Kalamazoo-Portage, MI metro. The weather load is 19 days of clearing, about 50 inches of snow in total, with 129 freezing days. County life expectancy is 77.1 years against 77.1 nationally. Anyone planning fifteen more years in this house has the data on their side. The number that matters most is the last one: the house takes $623 a month even with no mortgage on it, or 14% of typical 65+ income.
Sources: U.S. Census Bureau, American Community Survey 2020-2024 5-Year Estimates; county and city millage records; County Health Rankings & Roadmaps 2025, at county level; NOAA 1991-2020 Climate Normals; U.S. Bureau of Economic Analysis Regional Price Parities; the MDHHS designated trauma facility list, with road distances from OSRM; the municipal code cited above. This product uses the Census Bureau Data API but is not endorsed or certified by the Census Bureau.
How the process works, step by step
Here is the path from first call to funding:
Want the full walkthrough? See how a reverse mortgage works, step by step.
Why work with a mortgage broker, not a bank
As a broker with C2 Financial, I am not tied to one company’s rate sheet. I shop your loan across more than 30 wholesale reverse-mortgage lenders. First, pricing: even a standard HECM is priced differently from lender to lender, so shopping the same loan can mean a lower rate or more available funds. Second, product access: brokering opens the door to the proprietary and jumbo programs a single bank cannot offer.
I broker through C2 Financial Corporation (NMLS #135622), a national mortgage brokerage.
How much a reverse mortgage costs in Kalamazoo
On a standard FHA HECM you can expect a fixed or adjustable interest rate; FHA mortgage insurance (an upfront premium of 2% of value plus 0.5% per year), which funds the FHA guarantee behind the non-recourse protection; an FHA-capped origination fee ($6,000 max); and third-party closing costs. Most costs can be rolled into the loan, and I will give you a full, itemized breakdown before you commit to anything.
For an itemized breakdown of every fee, and what is financed versus paid up front, see what a reverse mortgage costs.
What happens to your home and your heirs
You keep the title and you keep ownership. A reverse mortgage is a non-recourse loan, so you and your heirs can never owe more than the home is worth when the loan is repaid. It comes due when the last borrower permanently leaves; your heirs can repay or refinance to keep the home, or sell and keep every dollar of remaining equity. If the balance ever exceeds the value, FHA insurance covers the difference and heirs can settle a HECM for 95% of appraised value.
The full heirs and estate walkthrough, including timelines and the 95% rule, is on how it works.
What about condos and HOA approval?
Some of Kalamazoo’s 62-plus owners live in condos or HOA communities, and those bring their own rules. A standard HECM requires the whole condo project to be FHA-approved, and many buildings are not on that list. A proprietary loan can often finance a non-approved or non-warrantable condo. First, I check your building. If condos are on your mind, start with my HOA checklist.
See the full property and eligibility rules on the requirements page.
The HUD counseling requirement, explained
Federal HUD rules require independent counseling before you close, on every HECM, in every state. You meet with a HUD-approved counselor who confirms you understand the loan. It is a consumer protection, usually low-cost or free. Find approved counselors through HUD’s HECM program, and the Michigan Department of Insurance and Financial Services offers consumer guidance. HUD publishes the approved counselors serving Kalamazoo County, so scheduling never has to stall your file.
For what the counseling session actually covers, see the counseling page.
Kalamazoo neighborhoods and nearby areas I serve
I work with homeowners across the city and greater Kalamazoo County. That includes Stuart, Vine, Westnedge Hill, Winchell, Milwood, and Edison. Core ZIP codes include 49001, 49006, 49007, 49008, 49048.
In addition, I also help owners in nearby communities such as Portage, Oshtemo, Comstock, Parchment, Kalamazoo Township, and Galesburg, and across Kalamazoo, Van Buren, and Calhoun counties. See every area I cover on my reverse mortgages across Michigan page. Do not see your area? Reach out and ask.
If aging in place is your goal, local resources like Milestone Senior Services can help you plan, and my free Aging-in-Place Home Scorecard lets you score any Kalamazoo home in about 15 minutes to see how ready it is to grow old in.
Wondering whether a home is one you could grow old in? Score any home in about 15 minutes, and see how a reverse mortgage can fund the upgrades.
Use the Aging-in-Place Scorecard →Reverse mortgage FAQs for Kalamazoo homeowners
Is a reverse mortgage line of credit in Kalamazoo tax-free, and does it grow?
The money you draw is loan proceeds, not income, so it is generally tax-free, and the unused part of a HECM line of credit grows over time, independent of your home’s value. That makes it a flexible standby you open now and tap later. Here is how the growing line of credit works.
Can I get a reverse mortgage on a Kalamazoo condo?
A standard FHA HECM needs the whole condo project to be FHA-approved, and many buildings are not. When that is the case, a proprietary reverse mortgage can usually finance a non-approved or non-warrantable condo. I check your specific building first.
Do I still own my home?
Yes. The title stays in your name. You keep ownership and can sell or move whenever you want. The loan is repaid when the last borrower permanently leaves, and you or your heirs keep any remaining equity.
How much can I borrow in Kalamazoo?
It depends on the youngest borrower’s age, current rates, and your home value. Most Kalamazoo homes fall within the standard FHA HECM limit, while higher-value homes may also fit a jumbo program that exceeds it.
Is HUD counseling required in Kalamazoo?
Yes. You must complete a session with a HUD-approved counselor before closing. It is usually low-cost or free. HUD publishes the approved counselors serving Kalamazoo County, so scheduling never has to slow you down.
What are the age and equity requirements?
A standard FHA HECM starts at age 62. Some proprietary programs start at 55. You also need significant equity, and the home must be your primary residence.
Do I still pay property tax with a reverse mortgage in Kalamazoo?
Yes. With a reverse mortgage you keep title and remain responsible for property taxes, homeowners insurance, and upkeep. Depending on your age and income you may qualify for senior property-tax relief in Michigan (the programs vary by state and by county), and you can use reverse-mortgage funds to help cover those ongoing costs.
Can I use a reverse mortgage to buy a smaller home in Kalamazoo?
Yes, that’s a HECM for Purchase. It lets buyers 62+ put down a portion of the price and finance the rest with a reverse mortgage, so you can right-size into a single-level or lower-maintenance Kalamazoo home without taking on a monthly mortgage payment.
Have a question about a reverse mortgage in Kalamazoo? Call or text me at 720-449-6622.
Quick guide: is a reverse mortgage right for me?
First, answer four short questions, and the guide will point you toward the resource that fits your situation. Of course, it is general guidance for learning, not an approval or a quote, and nothing you tap is stored.
Free guide: Your Home Can Help
My complete guide to reverse mortgages for Michigan homeowners, the retirement squeeze, the myths, your options, real client stories, and what it really costs. No email required.
Learn how reverse mortgages work
Want the full details before we talk?
Reverse mortgages in nearby communities
About Christopher Gibson
Christopher Gibson (NMLS #1910430) is an independent mortgage and reverse mortgage broker with C2 Financial Corporation (NMLS #135622), serving homeowners across the states he is licensed in. Serving Kalamazoo and nearby communities. Call or text 720-449-6622. More about Christopher.
Read reviews of Reverse Mortgages & Home Loans with Christopher Gibson at C2 Financial
Google Business Profile → · Mortgage Matchup →
*This is general information, not tax advice. Reverse mortgage proceeds are loan advances rather than income and are generally not subject to federal income tax. Consult a CPA or tax advisor about your specific situation. Receiving loan proceeds may also affect eligibility for need-based government benefits such as Medicaid or Supplemental Security Income (SSI).