The Ultimate HOA Checklist Before Getting a Reverse Mortgage on a Condo
TL;DR: Yes, you can usually get a reverse mortgage on a condo. Three things decide it: whether the project is FHA-approved, whether your unit clears FHA Single-Unit Approval, or whether you skip FHA altogether with a proprietary loan. Notice that all three are about the building, not about you. That is why the six questions below go to the HOA before you pay for anything.
Evaluating the HOA on a Condominium for an FHA Reverse Mortgage

This guide is for real-estate agents, financial advisors, and savvy homeowners evaluating the HOA on a condominium for an FHA reverse mortgage. Use it to avoid expensive surprises and loan denial.
- Litigation: any pending lawsuits or structural disputes involving the HOA?
- Dues delinquency: are more than 15% of units 60+ days past due on dues?
- Single ownership: does any single owner or entity own more than 10% of the units?
- Commercial use: does commercial space make up more than 35% of the property?
- Owner-occupancy: is owner-occupancy above 50%?
- Deferred maintenance: any deferred maintenance that could require owners to vacate their units for repairs?
Quick Wins When Evaluating the HOA on a Condominium for an FHA Reverse Mortgage
- Verify ≥ 50 % owner-occupancy and < 15 % delinquencies.
- Scan the HUD-9991 form before paying for a condo cert.
- Check the master policy for 100 % replacement cost and deductibles under $10 k.
- Email the 10 questions in Step 6 first, save time and money.
FHA condo approval requirements, in full
A reverse mortgage on a condo runs on FHA rules, because a HECM is FHA-insured. A condo qualifies one of two ways: the whole project is FHA-approved, or your individual unit clears FHA Single-Unit Approval. Either way, the building has to meet the standards below. These figures reflect current FHA guidance (HUD Handbook 4000.1 and Mortgagee Letter 2019-13).
Project and building requirements
- Owner-occupancy: at least 50% of units owner-occupied rather than rented.
- Dues delinquency: no more than 15% of units 60+ days past due on HOA dues.
- Commercial space: no more than 35% of the project used for commercial or non-residential space.
- Single-owner concentration: no single owner or entity holds more than 10% of the units (in projects of 5 to 20 units, no single owner may hold more than one unit).
- FHA concentration: no more than 10% of units already carry FHA loans (in projects of 5 to 9 units, no more than two).
- Reserves: at least 10% of the annual budget funding reserves, ideally backed by a current reserve study.
- Insurance: 100% replacement-cost hazard coverage, adequate liability, a fidelity bond for larger associations, and flood insurance where FEMA requires it.
- Litigation: no pending litigation that affects the safety, soundness, structure, or finances of the project.
- Deferred maintenance: no deferred maintenance serious enough to affect safety or require owners to vacate.
Single-Unit Approval: the second door
If the whole building is not approved, FHA can still approve your individual unit when:
- The project is existing construction, fully complete, with the certificate of occupancy issued at least one year ago and no further phasing.
- The project has at least 5 units.
- The building meets the owner-occupancy, delinquency, commercial-space, insurance, and litigation standards above.
- The unit will be a primary residence or second home, not an investment property.
The third door: a proprietary reverse mortgage
TL;DR: Everything above this point assumes a HECM, which is FHA-insured, which is the only reason the building has to be on FHA’s list. A proprietary reverse mortgage is not FHA-insured, and it is not a Fannie Mae or Freddie Mac loan either. It is the lender’s own money, held in portfolio, so the lender writes the condo rules. Those rules are a lot less strict than FHA’s, and on a condo a proprietary loan is often the better fit from the start rather than the fallback.
I use this constantly. Half the condo files I take are buildings that would pass FHA on the merits and simply are not on the list, and nobody involved wants to spend two months getting them there.
What you stop worrying about
- Being on the list at all. No project approval, no Single-Unit Approval, no HUD-9991. The lender has never heard of HUD’s roster and does not need to.
- The FHA concentration cap. No more than 10% of units already carrying FHA loans, or two units in a project of 5 to 9. That rule says nothing about how the building is run, and it kills small buildings for no good reason.
- A management company that will not do FHA paperwork. Plenty of them will not, as a matter of policy. That is not a red flag about the building. It is a wall, and this walks around it.
- Age 62. A HECM requires age 62+. Proprietary programs generally start at age 55.
- The HECM lending limit, $1,249,125 in 2026. Above that, FHA stops counting your equity. Proprietary programs go considerably higher.
- FHA mortgage insurance. No upfront premium and no annual premium, because there is no FHA insurance on the loan.
What the lender still looks at
Less strict is not no rules. The lender still reviews the project, and what it cares about is whether the building is insurable and financially sound. Active litigation over structure or safety, an association that cannot get a master policy, serious deferred maintenance, an evacuation order. Those are problems for any lender on any product, and nothing makes them go away.
The real difference is judgment versus checklist. A proprietary underwriter looks at the whole building and makes a call. FHA runs a list, and one number out of range ends it.
The trade-offs
- A minimum value. Most proprietary programs want a home worth roughly $450,000 or more. On a modest condo this rules the option out before anything else does.
- Age 55 is eligibility, not advice. At age 55 the proceeds are a much smaller share of the value than they are at 75. Being eligible and being well served are two different questions.
- State age floors are not all 55. Across the states I am licensed in, Colorado, Florida and Michigan start at 55. Washington starts at 60. Texas requires 62, the same as a HECM, so in Texas the age advantage disappears entirely.
- Rate. Proprietary money generally prices above a HECM.
- Program to program. Two proprietary lenders will not always give you the same answer on the same building. That is exactly the argument for running it through a broker instead of one bank.
- Counseling anyway. HUD-approved counseling is still required. That does not go away.
When I reach for it
- The building is genuinely fine and simply is not FHA-approved, and nobody wants to run the approval.
- The management company will not complete FHA paperwork.
- The borrower is under 62 and the numbers still work.
- The home is worth more than the HECM limit, so FHA is leaving equity on the table.
- The building trips one FHA-specific rule, like the concentration cap, that has nothing to do with how the place is run.
Where it does not help: if the building failed on litigation, insurance or serious structural repairs, no product fixes that. At that point you are in non-warrantable condo territory, and a condotel is almost always a no on any reverse mortgage. More on how the products differ is in types of reverse mortgages.
Send me the address and the HOA’s answers to the six questions above and I will tell you which of the three doors is open, usually the same day. Call or text 720-449-6622.
Reverse Mortgage Calculator
Let’s calculate how much equity you can unlock.
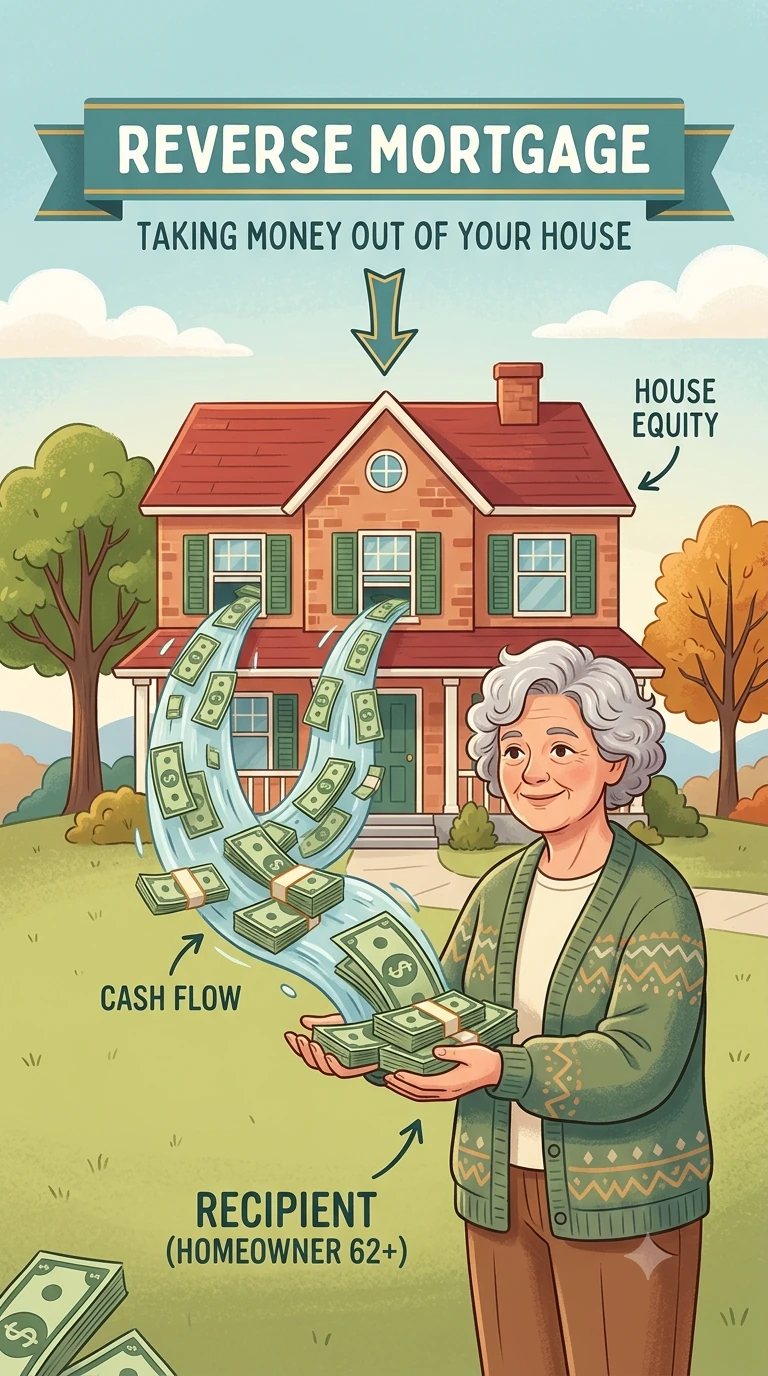
A reverse mortgage is a loan. The balance grows over time and is repaid when the last borrower leaves the home. You keep the title, and you remain responsible for property taxes, homeowners insurance, and upkeep.
- 1Property
- 2Value
- 3About You
- 4Your Estimate
This form collects information so Christopher Gibson can prepare a personalized estimate. It does not generate a quote, an approval, or an offer of credit, and nothing here is a commitment to lend. Final terms depend on a complete application, underwriting review, a HUD-approved appraisal, and the rates in effect at the time of lock. HUD requires independent counseling before any HECM closes. Your information is secure and never sold. Christopher Gibson, NMLS #1910430. Equal Housing Opportunity. Privacy Policy.
Step 1. FHA Spot-Approval Basics for Evaluating the HOA on a Condominium
- Project complete, no active construction.
- ≥ 5 units, ≥ 50 % owner-occupied.
- ≤ 10 % FHA concentration (max 2 units if < 10 total).
- No unresolved litigation or financial distress.
Step 2. HOA Financial Health When Evaluating the HOA on a Condo for an FHA Reverse Mortgage
- ≥ 10 % of budget to reserves or a reserve study < 24 months old.
- Delinquencies below 15 %.
- Operating and reserve funds in separate accounts.

Step 3. Insurance Traps When Evaluating the HOA on a Condominium for an FHA Reverse Mortgage
- 100 % replacement-cost hazard coverage.
- ≥ $1 M liability.
- Fidelity bond if 20+ units or >$50 k in funds.
- Flood insurance if required by FEMA.
Watch out: massive deductibles on roofs or “walls-in” exclusions.
Step 4. Deal-Killers That Stop an FHA Reverse Mortgage on a Condo
- Reserves underfunded or no recent study.
- Delinquencies > 15 %.
- Pending structural litigation.
- Commercial space > 35 %.

Step 5. General HOA Health Tips for an FHA Reverse Mortgage
- Reserve study funded ≥ 70 %.
- Budgets & meeting minutes readily available.
- Common areas kept in good repair.
Step 6. Pre-Screen Email While Evaluating the HOA on a Condominium
Copy and paste this email and send it to the management company before you pay for a condo questionnaire. You usually hear back the same day, for free.
Subject: A few quick questions before I order the HOA questionnaire
Hello,
I am working with a homeowner at [address] on an FHA-insured loan. Before I order and pay for the formal lender condo questionnaire, I want to respect your time and make sure we will not run into a basic eligibility roadblock. Could you confirm whether any of the following apply to the HOA?
- Deferred maintenance: is there any deferred maintenance that could require owners to vacate their units for repairs?
- Litigation: any pending lawsuits or structural disputes involving the HOA?
- Dues delinquency: are more than 15% of units 60+ days past due on monthly dues?
- Single ownership: does any single owner or entity own more than 10% of the units?
- Commercial use: does commercial space make up more than 35% of the property?
- Owner-occupancy: is owner-occupancy above 50%?
- Insurance: could you send me the master insurance policy?
- Special assessments: are there any current or planned special assessments?
- Construction and control: is the HOA still developer-controlled, or is any part of the project still under construction?
- Short-term rentals: does the HOA run any short-term-rental or hotel-like operations?
If none of these are an issue, we will go ahead and order the standard questionnaire through your preferred portal. Thank you for your help.
Christopher Gibson
C2 Financial, NMLS #1910430
720-449-6622
Frequently Asked Questions
What makes a condo ineligible for an FHA loan or reverse mortgage?
High delinquencies, low reserves, litigation, or missing insurance.
Can you get a reverse mortgage on a condominium?
Usually yes. There are three routes: the project is FHA-approved, your individual unit clears FHA Single-Unit Approval, or you use a proprietary reverse mortgage, which is not FHA-insured and does not require either one.
What should I ask the HOA first?
Occupancy, delinquencies, reserves, insurance, assessments, litigation.
Can I get a reverse mortgage on a condo that is not FHA approved?
Yes, through a proprietary reverse mortgage. It is not FHA-insured, so the project does not need to be on HUD’s approved list and your unit does not need Single-Unit Approval. The lender reviews the building against its own guidelines, which are considerably less strict than FHA’s. Most proprietary programs start at age 55 and want a home worth roughly $450,000 or more.
Does a proprietary reverse mortgage need FHA spot approval?
No. Single-Unit Approval, which people still call spot approval, is an FHA process for an FHA-insured HECM. A proprietary reverse mortgage is not FHA-insured, so it is not part of that process at all. That is exactly why the proprietary option gets used when spot approval is unavailable or the association will not participate.
What if the HOA will not complete the FHA questionnaire?
It happens, and it is usually policy rather than a warning sign about the building. A HECM cannot proceed without it. A proprietary reverse mortgage can, because there is no HUD form in the file. This is one of the most common reasons I move a condo file to a proprietary program.

About the Author
Christopher Gibson is a mortgage loan officer licensed in CO, FL, MI, TX, and WA, and a former real-estate agent. He specializes in FHA reverse mortgages and condo lending strategies.
Next step: Download the HOA checklist & email template (PDF) to screen any condo before applying.
Need advice? Email Chris directly.
Want the full details before we talk?
Reverse mortgages by state
Condo rules are federal, but I work your file locally. I am licensed in five states, so start with your state hub for local details:
- Washington reverse mortgages
- Colorado reverse mortgages
- Texas reverse mortgages
- Florida reverse mortgages
- Michigan reverse mortgages
Keep reading
If a condo is on your radar for a reverse mortgage, it helps to understand how much you can get from a reverse mortgage, the requirements to qualify, and what a reverse mortgage costs. Grab the free reverse mortgage guide, see what a condotel is and why Fannie & Freddie reject non-warrantable condos, or explore your reverse mortgage options and get in touch to review your specific building.
Read reviews of Reverse Mortgages & Home Loans with Christopher Gibson at C2 Financial
Google Business Profile → · Mortgage Matchup →
About Christopher Gibson
Christopher Gibson (NMLS #1910430) is an independent mortgage and reverse mortgage broker with C2 Financial Corporation (NMLS #135622), serving homeowners across Washington, Colorado, Texas, Florida, and Michigan. He holds a 5.0-star Google rating. Call or text 720-449-6622.