← Reverse mortgages in Michigan
Does the bank own your home if you take a reverse mortgage in Holland? No, and it is the question I hear most. Your name stays on the title and the deed, exactly like any mortgage, and the lender simply holds a lien. As long as you live there and keep up the taxes, insurance, and upkeep, the home stays yours. On a typical $376K Holland home in Ottawa County, a longtime owner puts real equity to work without giving up ownership.
A typical Holland home is worth around $376K, and for a longtime owner it is usually paid off with real equity behind it. A reverse mortgage only fits some situations, and I will say so when it does not. See how Holland compares on my Michigan aging-in-place overview.
Updated
On this page
- Local reverse mortgage broker in Holland
- Aging in place in Holland
- What is my Holland home worth?
- How does a reverse mortgage work in Holland?
- Who qualifies for a reverse mortgage in Holland?
- Reverse mortgage calculator
- Cost of aging in place
- Is a reverse mortgage right for me?
- Learn how reverse mortgages work
- Jumbo reverse mortgages in Holland
- Why work with a broker, not a bank
- How much a reverse mortgage costs in Holland
- Reverse mortgage rates in Holland
- Condos and HOA
- Reverse mortgage FAQs
Reverse Mortgage Specialist in Holland, MI
Who is a local reverse mortgage broker in Holland, MI? Christopher Gibson (NMLS #1910430) is an independent broker with C2 Financial Corporation (NMLS #135622). He helps Holland homeowners age 55 and older (age 62+ for the government-insured HECM) turn home equity into funds for retirement. Because the funds are loan proceeds rather than income, they are generally not subject to federal income tax.* Call or text 720-449-6622.
Aging in place in Holland, at a glance
The pros and cons, every measure I track, sorted by which way it cuts. Full detail below.
| Works in your favor | Neutral or mixed | Plan around it |
|---|---|---|
|
|
|
Figures: U.S. Census ACS 2020-2024 5-Year; County Health Rankings 2025 (life expectancy, county level); NOAA 1991-2020 Climate Normals; FEMA National Risk Index (per hazard, not the composite). This product uses the Census Bureau Data API but is not endorsed or certified by the Census Bureau.
Why a reverse mortgage appeals to Holland homeowners 55+ attempting to age in place
Holland is a Dutch-heritage town known for its tulips near Lake Michigan. Homes bought decades ago now run around $376K and are usually mortgage-free, and that paid-off equity is real money on a fixed income. A reverse mortgage turns some of it into cash flow while you stay in the home.
Holland’s strong Dutch heritage and tight-knit community keep many retirees rooted in the same homes for decades, building substantial equity along the Lake Macatawa shoreline and in the historic core. Fixed incomes can strain against rising taxes and the upkeep of older housing stock, making a HECM a practical way to unlock value without leaving town. With typical values in the high $300Ks, nearly all local seniors qualify under standard FHA limits.
Holland reverse mortgage facts and figures
Holland is affordable by Michigan standards, and that affordability is exactly what lets home equity stretch a fixed income here. Here are a few numbers worth knowing:
Home values: Zillow, mid-2026. HECM limit: HUD/FHA 2026. Property tax: U.S. Census. Figures change, so ask me for today’s numbers on your home.
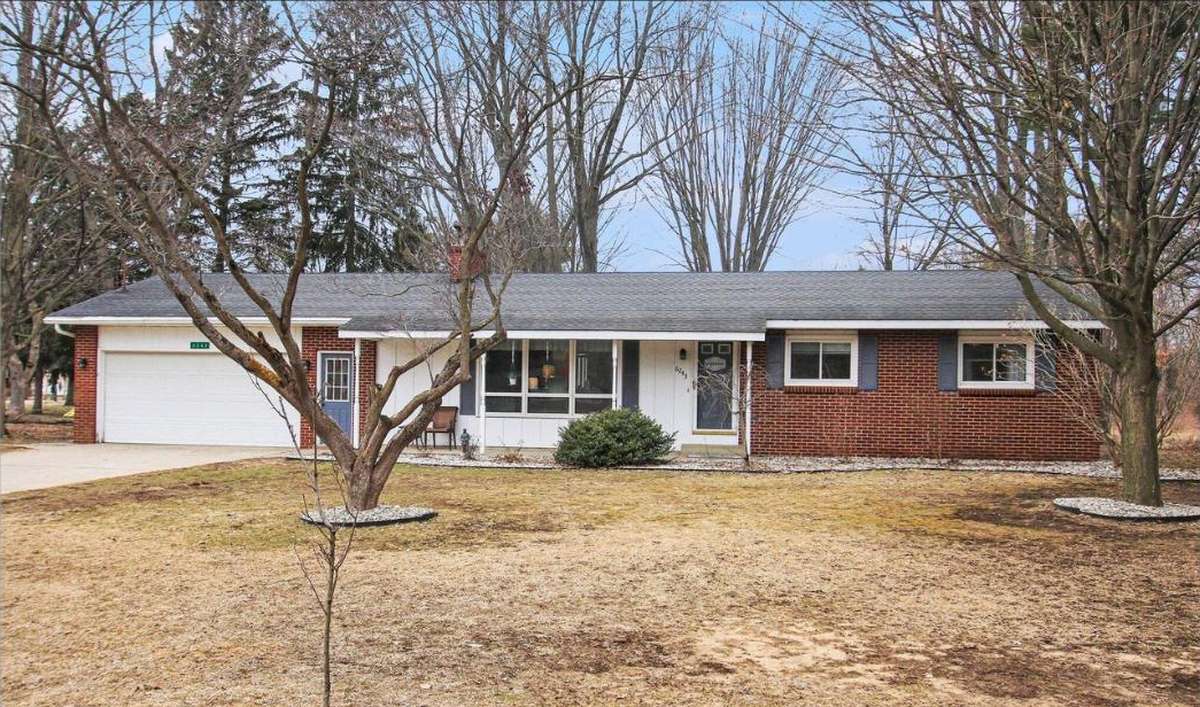
What is your Holland home worth today?
Curious what your home could be worth, and how much equity you have to work with? Use my free home-value tool below. Enter your address for an instant Holland estimate you can track over time, at no cost and no obligation.
Jumbo reverse mortgages in Holland (HECM vs. jumbo)
Most homes here are covered by the government-insured HECM, while higher-value homes and many condos fit a proprietary jumbo. For the full side-by-side of HECM, jumbo, HELOC, and HEI, see the reverse mortgage comparison table, or the types of reverse mortgages for a plain-English rundown.
For a full side-by-side of every program and how to choose, see the types of reverse mortgages.
Buying a home? Consider a HECM for Purchase (H4P)
A HECM for Purchase lets you buy your next home using a reverse mortgage, so you put down a portion and finance the rest with no required monthly principal-and-interest payment. For a Holland owner trading an older two-story for a single-level place, it is a clean way to move without taking on a new monthly payment.
How much you can access depends on age, rates, and value. Start your own estimate with the reverse mortgage calculator below.
Reverse Mortgage Calculator
Let’s calculate how much equity you can unlock.
A reverse mortgage is a loan. The balance grows over time and is repaid when the last borrower leaves the home. You keep the title, and you remain responsible for property taxes, homeowners insurance, and upkeep.
Aging in place in Holland with a reverse mortgage: what it really costs
The specifics for Holland, drawn from public records rather than from a brochure. These come from federal and municipal sources, and I name them at the bottom.
Before the numbers: the state of the building
Look up the building stock and you get 1966, right at the Michigan median of 1972. About 63% of the housing here went up before 1980, which is the line that matters for lead paint. What trips files here is condition, not value. FHA appraisers write up roofs near the end of their life, furnaces that fail to fire, and lead-paint surfaces on pre-1978 houses. Each of those is solvable through a repair set-aside funded from your own loan.
Taxes, insurance, utilities: the permanent bill
Keeping a paid-off house in Holland runs a median $560 a month. Taxes, insurance, heat, power, water, and an association fee if there is one. A typical household aged 65 and over here brings in $58,161, so the house takes 12% of it. The Census counts 29% of Holland owners 65 and over as cost-burdened, meaning 30% or more of income goes to housing. A reverse mortgage cannot touch this. What it can do is put a tenure payment behind it so the money is there every month.
Snow, sidewalks and liability
On average, 23 days a year need clearing here. Clearing it is a legal duty here, not a neighborly one: 24 hours for snow, and 12 hours to salt or sand ice once it forms. The teeth in it: a municipal civil infraction. That is Holland Code 39-10.04. Holland is unusual: the city runs a municipal sidewalk plowing program and clears many walks itself, even though the owner’s duty still stands. Worth asking neighbors what they pay. It is usually less than people expect.
Rides to the clinic and the grocery store
The service that covers Holland is the Macatawa Area Express, MAX, and its Reserve-A-MAX dial-a-ride, open to the senior fare starts at 65. Pricing: $2.30 for a dial-a-ride trip, 50 cents on a fixed route. A ride service you are registered with is a very different thing from one that exists.
The statutory layer, and a link to the detail
The short version of Michigan law: MCL 211.27a(7)(j) means a reverse mortgage does not uncap your taxable value, and keeping title means you keep the 18-mill Principal Residence Exemption. The Michigan page covers the rest.
Who pays for senior services here, and how
There is a dedicated senior services millage here, levied by Allegan County Senior Services, which covers the Allegan County side of the city while the Ottawa County side has no senior millage at all, 0.4753 mill. The money goes to door-to-door senior rides at no cost to the rider, home-delivered meals, adult day services and personal emergency response. I would rather someone use the millage and take a smaller loan than the reverse.
The hospital, and the drive on the worst day
Holland has a hospital of its own, Holland Hospital, which is independent rather than part of a system, with a strategic alliance with University of Michigan Health. On road distance rather than as the crow flies, University of Michigan Health West is 24 miles away and rated Level II; Level I is 30 miles in Grand Rapids. Take it as one input among several, but do not leave it out.
Reading the data on Holland
Normals give this 23 shoveling days, 70 inches of snowfall, and 131 days that never get above freezing. County Health Rankings puts life expectancy here at 80.1 years against 77.1 for the US. Budget for more years under this roof than the averages would suggest. Regional price parity comes out at 96 with the US at 100, computed over Grand Rapids-Wyoming-Kentwood, MI metro. Put together, keeping a paid-off home here runs a median $560 a month, or 12% of what a typical 65+ household brings in.
Sources: U.S. Census Bureau, American Community Survey 2020-2024 5-Year Estimates; the municipal code cited above; county and city millage records; County Health Rankings & Roadmaps 2025, at county level; NOAA 1991-2020 Climate Normals; U.S. Bureau of Economic Analysis Regional Price Parities; the MDHHS designated trauma facility list, with road distances from OSRM. This product uses the Census Bureau Data API but is not endorsed or certified by the Census Bureau.
Who qualifies for a reverse mortgage in Holland?
Qualifying for a reverse mortgage in Holland comes down to a few clear tests. For an FHA HECM you generally need to be at least 62, and the home has to be your primary residence. You also need enough equity, and most longtime owners are well past that threshold. A HECM has no income or credit-score cutoff the way a traditional loan does, though there is a financial assessment to confirm you can keep up with property taxes, insurance, and upkeep. If you are 55 to 61, a proprietary program may still fit. The quickest way to see where you stand is to run your own numbers with the Holland reverse mortgage calculator below, or read the full reverse mortgage requirements. Not sure? Call or text me at 720-449-6622 and I will tell you plainly.
How does a reverse mortgage work in Holland?
Here is the path from first call to funding:
Want the full walkthrough? See how a reverse mortgage works, step by step.
Why work with a mortgage broker, not a bank
As a broker with C2 Financial, I am not tied to one company’s rate sheet. I shop your loan across more than 30 wholesale reverse-mortgage lenders. First, pricing: even a standard HECM is priced differently from lender to lender, so shopping the same loan can mean a lower rate or more available funds. Second, product access: brokering opens the door to the proprietary and jumbo programs a single bank cannot offer.
I broker through C2 Financial Corporation (NMLS #135622), a national mortgage brokerage.
How much a reverse mortgage costs in Holland
On a standard FHA HECM you can expect a fixed or adjustable interest rate; FHA mortgage insurance (an upfront premium of 2% of value plus 0.5% per year), which funds the FHA guarantee behind the non-recourse protection; an FHA-capped origination fee ($6,000 max); and third-party closing costs. Most costs can be rolled into the loan, and I will give you a full, itemized breakdown before you commit to anything.
For an itemized breakdown of every fee, and what is financed versus paid up front, see what a reverse mortgage costs.
Reverse mortgage rates in Holland and how they affect how much you can borrow
On a reverse mortgage, your interest rate does more than set what accrues, it helps decide how much you can access in the first place. The amount available to you (your principal limit) comes down to three things: the age of the youngest borrower, the expected interest rate, and your home value up to the FHA lending limit. All else equal, an older borrower and a lower rate both mean a larger available draw. Most Holland homes fall within the standard FHA HECM limit, while higher-value homes may also fit a jumbo program that exceeds it. For the mechanics, see how the principal limit is calculated, then put real numbers to it with the Holland reverse mortgage calculator.
What happens to your home and your heirs
You keep the title and you keep ownership. A reverse mortgage is a non-recourse loan, so you and your heirs can never owe more than the home is worth when the loan is repaid. It comes due when the last borrower permanently leaves; your heirs can repay or refinance to keep the home, or sell and keep every dollar of remaining equity. If the balance ever exceeds the value, FHA insurance covers the difference and heirs can settle a HECM for 95% of appraised value.
The full heirs and estate walkthrough, including timelines and the 95% rule, is on how it works.
What about condos and HOA approval?
Some of Holland’s 62-plus owners live in condos or HOA communities, and those bring their own rules. A standard HECM requires the whole condo project to be FHA-approved, and many buildings are not on that list. A proprietary loan can often finance a non-approved or non-warrantable condo. First, I check your building. If condos are on your mind, start with my HOA checklist.
See the full property and eligibility rules on the requirements page.
The HUD counseling requirement, explained
Federal HUD rules require independent counseling before you close, on every HECM, in every state. You meet with a HUD-approved counselor who confirms you understand the loan. It is a consumer protection, usually low-cost or free. Find approved counselors through HUD’s HECM program, and the Michigan Department of Insurance and Financial Services offers consumer guidance. HUD publishes the approved counselors serving Ottawa County, so scheduling never has to stall your file.
For what the counseling session actually covers, see the counseling page.
Holland neighborhoods and nearby areas I serve
I work with homeowners across the city and greater Ottawa County. That includes Downtown Historic District, Washington Square, Waukazoo, Maplewood, Macatawa Park, and Montello Park. Core ZIP codes include 49423, 49424.
In addition, I also help owners in nearby communities such as Zeeland, Park Township, Saugatuck, Douglas, Hamilton, and West Olive, and across Ottawa, and Allegan counties. See every area I cover on my reverse mortgages across Michigan page. Do not see your area? Reach out and ask.
If aging in place is your goal, local resources like Evergreen Commons can help you plan, and my free Aging-in-Place Home Scorecard lets you score any Holland home in about 15 minutes to see how ready it is to grow old in.
Wondering whether a home is one you could grow old in? Score any home in about 15 minutes, and see how a reverse mortgage can fund the upgrades.
Use the Aging-in-Place Scorecard →Reverse mortgage FAQs for Holland homeowners
Can I get a reverse mortgage on a Holland condo?
A standard FHA HECM needs the whole condo project to be FHA-approved, and many buildings are not. When that is the case, a proprietary reverse mortgage can usually finance a non-approved or non-warrantable condo. I check your specific building first.
Do I still own my home?
Yes. The title stays in your name. You keep ownership and can sell or move whenever you want. The loan is repaid when the last borrower permanently leaves, and you or your heirs keep any remaining equity. Here is who owns the home.
Is HUD counseling required in Holland?
Yes. You must complete a session with a HUD-approved counselor before closing. It is usually low-cost or free. HUD publishes the approved counselors serving Ottawa County, so scheduling never has to slow you down.
What are the age and equity requirements?
A standard FHA HECM starts at age 62. Some proprietary programs start at 55. You also need significant equity, and the home must be your primary residence.
Do I still pay property tax with a reverse mortgage in Holland?
Yes. With a reverse mortgage you keep title and remain responsible for property taxes, homeowners insurance, and upkeep. Depending on your age and income you may qualify for senior property-tax relief in Michigan (the programs vary by state and by county), and you can use reverse-mortgage funds to help cover those ongoing costs.
Can I use a reverse mortgage to buy a smaller home in Holland?
Yes, that’s a HECM for Purchase. It lets buyers 62+ put down a portion of the price and finance the rest with a reverse mortgage, so you can right-size into a single-level or lower-maintenance Holland home without taking on a monthly mortgage payment.
Have a question about a reverse mortgage in Holland? Call or text me at 720-449-6622.
Quick guide: is a reverse mortgage right for me?
First, answer four short questions, and the guide will point you toward the resource that fits your situation. Of course, it is general guidance for learning, not an approval or a quote, and nothing you tap is stored.
Free guide: Your Home Can Help
My complete guide to reverse mortgages for Michigan homeowners, the retirement squeeze, the myths, your options, real client stories, and what it really costs. No email required.
Learn how reverse mortgages work
Want the full details before we talk?
Reverse mortgages in nearby communities
About Christopher Gibson
Christopher Gibson (NMLS #1910430) is an independent mortgage and reverse mortgage broker with C2 Financial Corporation (NMLS #135622), serving homeowners across the states he is licensed in. Serving Holland and nearby communities. Call or text 720-449-6622. More about Christopher.
Read reviews of Reverse Mortgages & Home Loans with Christopher Gibson at C2 Financial
Google Business Profile → · Mortgage Matchup →
*This is general information, not tax advice. Reverse mortgage proceeds are loan advances rather than income and are generally not subject to federal income tax. Consult a CPA or tax advisor about your specific situation. Receiving loan proceeds may also affect eligibility for need-based government benefits such as Medicaid or Supplemental Security Income (SSI).