Can I Get a Mortgage on a Manufactured Home?
Yes, if the home was built after June 15, 1976, sits on a permanent foundation, and is titled as real property. Meet those three and you are shopping normal mortgages: FHA, VA, USDA, Fannie and Freddie. Miss any one of them and you are in chattel territory, where the money costs a lot more.
Modular, manufactured, mobile: the words matter to the lender
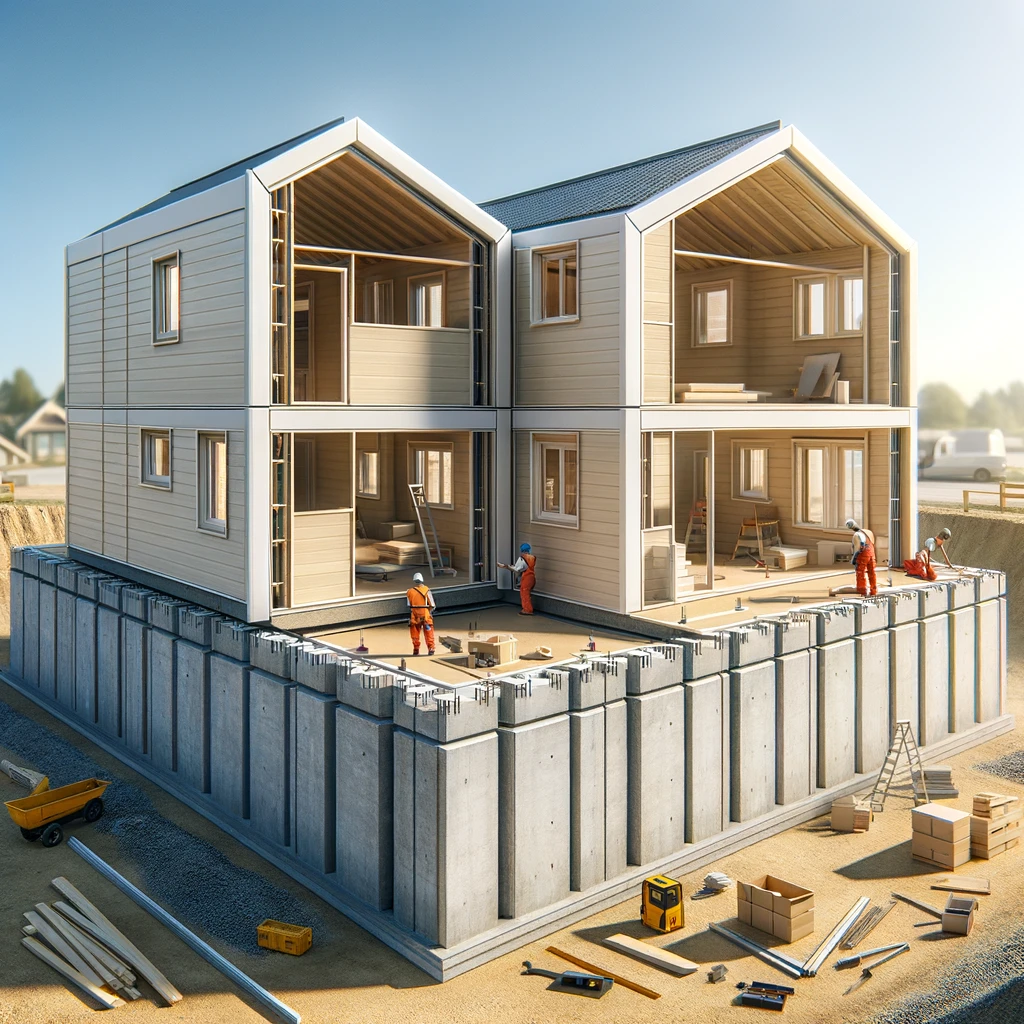
A modular home is built in a factory to the same state and local building codes as a site-built house, then set on a conventional foundation. It has no permanent chassis and no HUD tag. Fannie Mae treats modular, panelized and sectional housing the same as site-built, and so do FHA, VA and USDA. For financing purposes, a modular home is a house. Appraised on the standard form, titled as real property from day one, no special program needed.
A manufactured home is built to the federal HUD Code on a permanent steel chassis. Two markers prove it: the metal certification label on the exterior at the taillight end of each section, and the paper data plate inside, usually in a cabinet or closet. A manufactured home starts life as personal property, like a vehicle, and becomes real property only when it is permanently affixed and the title is surrendered under state law.
A mobile home is the pre-1976 term. Anything built before the HUD Code took effect on June 15, 1976 cannot be financed with an FHA, VA, USDA, Fannie or Freddie loan. No exceptions, no matter how well it has been maintained.
Getting the label wrong costs weeks. When an appraiser codes a modular home as manufactured, the fix is pulling the building permits and a manufacturer’s letter to prove there was never a chassis, and that happens while the clock on your contract keeps running. Find the data plate and the certification label before you write the offer, or confirm they do not exist.

FHA on a manufactured home
FHA finances manufactured homes as real estate under Title II when the home and the land are covered by one mortgage. The requirements are specific:
- At least 400 square feet of floor area
- Built on or after June 15, 1976 to the HUD Code
- Classified as real estate under state law
- A permanent foundation certified to HUD’s Permanent Foundations Guide for Manufactured Housing, signed by a licensed engineer
- Running gear removed: axles, wheels and towing hitch
- Finished grade at or above the 100-year flood elevation
- Maximum term of 30 years
The loan limits are the standard FHA limits, not a lower manufactured-home schedule: $541,287 in most counties for 2026, up to $1,249,125 in the highest-cost counties, with 3.5% down at a 580 score.
The foundation certification is where these deals usually stall. If the home was set years ago by someone who is long gone, an engineer has to inspect what is actually under it, and the answer is sometimes that piers and tie-downs need work before the loan can close. Order that inspection early, not during underwriting.
Conventional, and the two programs worth asking for by name
Standard conventional financing on a manufactured home runs to 95% LTV on a purchase, with 30-year fixed and ARM terms available. Single-wide homes are eligible for purchase and rate-and-term refinances, though not for cash-out.
Then there are the two upgrade programs, and they are meaningfully better:
- Fannie Mae MH Advantage. 3% down instead of 5%, and the 0.50% manufactured-housing loan-level price adjustment is waived. The home has to carry an MH Advantage sticker applied at the factory, and the site needs features like a driveway and a sidewalk to the door.
- Freddie Mac CHOICEHome. The same idea, with a construction spec: minimum 4/12 roof pitch, eaves, a porch or garage or dormer, upgraded insulation, permanent engineered foundation. As little as 3% down through Home Possible or HomeOne, the manufactured-housing credit fee waived, and the appraisal uses site-built comparables.
Both of these ask the home to look and perform like a site-built house, and in exchange they price like one. If a buyer is choosing a new home off a dealer’s lot, the sticker is worth asking about before they sign, because it cannot be added later.
Chattel loans, and why I try to avoid them
If the home stays personal property, usually because it sits on leased land in a park, the financing is a chattel loan: the home is the collateral, the land is not. The rate difference is not subtle. In the CFPB’s analysis of HMDA data, the median chattel rate was 8.6% against 4.9% for a manufactured-home mortgage and 4.1% for site-built. Terms are shorter too.
FHA’s Title I program is the government option in that space, with maximum loan amounts of $105,532 for a single-section home and $193,719 for a multi-section home, or $148,909 and $237,096 when the loan covers the home and lot together. Those figures date from March 2024 and HUD has not published a newer schedule.
Fannie and Freddie have bought essentially no chattel loans to date, though FHFA proposed a rewrite of the Duty to Serve rule in June 2026 directing both to build out responsible chattel programs. That is a proposal, not a rule, so plan around today’s market.
Where there is a path from chattel to a mortgage, it is usually worth taking: buy the land or secure a long enough ground lease, affix the home, retire the title, then refinance into real-property financing.
Converting the title to real property in the five states I lend in
Every state has its own paperwork for turning a manufactured home into real estate. The mechanism is what the lender’s title company will ask for:
- Washington: title elimination under RCW 65.20.040, amended by 2025 c 32 effective October 15, 2025
- Colorado: a Certificate of Permanent Location recorded with the county clerk and recorder, with the title purged under C.R.S. 38-29-118
- Texas: an election to treat the home as real property plus a Statement of Ownership filed with TDHCA under Occupations Code 1201.2055
- Florida: the title is retired and an RP decal issued under Florida Statute 319.261
- Michigan: an affidavit of affixture recorded with the register of deeds under MCL 125.2330i
If that step was never completed by a prior owner, the home is still personal property in the state’s eyes no matter how permanent it looks, and the conversion has to happen before the loan can close.
What to check before you write the offer
- Date of manufacture. On the data plate. Before June 15, 1976 ends the conversation.
- Certification label and data plate. Both present, legible, and photographed. A missing label means ordering a label verification letter from IBTS.
- Title status. Personal property or real property, and if it has been converted, get the recorded document.
- Foundation. Permanent, with the engineer’s certification in hand or budgeted for.
- Land. Owned, or a ground lease long enough for the loan term. Park-owned land changes the whole plan.
- Prior moves. Some programs will not finance a home that has been moved more than once from its original site.
Also worth knowing: HUD updated the HUD Code effective March 17, 2025, with about 90 new or revised standards, and for the first time it permits up to four dwelling units in a manufactured structure. Newer inventory is going to look less and less like the stereotype.
Where to start
I am licensed in Washington, Colorado, Texas, Florida and Michigan, and factory-built homes come up in all five. Send me the data plate photo and the address and I will tell you which programs the home qualifies for before you spend money on an appraisal. You can also run a payment on the mortgage calculator or see the full list of loan programs first. When you want the real answer for a specific home, call or text me at 720-449-6622.
Sources: 24 CFR 3280 (HUD Code definitions and labeling) and 24 CFR 203.43f (FHA Title II manufactured housing); HUD Mortgagee Letter 2025-23 (2026 FHA limits); FHA INFO 2024-08 (Title I limits); Fannie Mae Selling Guide B2-3-02 and B5-2-03 plus the MH Advantage product matrix; Freddie Mac CHOICEHome; CFPB, Manufactured Housing Finance: New Insights from HMDA; FHFA proposed Duty to Serve rule, June 24, 2026; state statutes as cited. Current as of September 2026.
Keep reading
Related: FHA vs conventional loans and the 2026 numbers and questions to ask a lender before you get pre-approved. See all loan programs I offer.
Frequently asked questions
Can I get a mortgage on a manufactured home?
Yes, when the home was built on or after June 15, 1976, sits on a permanent foundation, and has been converted to real property under state law. With those in place it qualifies for FHA, VA, USDA, Fannie Mae and Freddie Mac financing, with FHA starting at 3.5% down and MH Advantage or CHOICEHome starting at 3%.
What is the difference between a modular home and a manufactured home?
A modular home is built to state and local building codes, has no steel chassis and no HUD tag, and is financed exactly like a site-built house. A manufactured home is built to the federal HUD Code on a permanent chassis and carries a certification label and a data plate. That distinction, not the home’s appearance, is what determines which loan programs apply.
Can I finance a mobile home built before 1976?
Not with FHA, VA, USDA, Fannie Mae or Freddie Mac. Homes built before the HUD Code took effect on June 15, 1976 are ineligible for all of them. The remaining options are cash, a personal property or chattel lender, or seller financing.
Why are chattel loans more expensive?
A chattel loan is secured by the home only, not the land, so the lender has weaker collateral and no real estate to foreclose on. In the CFPB’s review of HMDA data the median chattel rate was 8.6% against 4.9% for a manufactured-home mortgage. If there is a path to owning the land and converting the title to real property, the refinance into a mortgage is usually worth the effort.
What does the foundation have to meet for an FHA loan?
A permanent foundation certified to HUD’s Permanent Foundations Guide for Manufactured Housing and signed by a licensed engineer, with the axles, wheels and hitch removed and the finished grade at or above the 100-year flood elevation. Order the engineer’s inspection early; retrofits are common on homes set years ago.
About Christopher Gibson
Christopher Gibson (NMLS #1910430) is an independent mortgage and reverse mortgage broker with C2 Financial Corporation (NMLS #135622), serving homeowners across Washington, Colorado, Texas, Florida, and Michigan. He holds a 5.0-star Google rating. Call or text 720-449-6622.