
Second Reverse Mortgage: Keep Your Low Rate and Take Cash Out
You want to get money out of your house. You do not want to give up the mortgage rate you are sitting on. I am Christopher Gibson, and this is the product people are usually shocked to find out exists. Every other reverse mortgage, including the government-insured HECM, has to be in first position, which means it pays your mortgage off. A second reverse mortgage does not. It is one of the types of reverse mortgages I can place, alongside the jumbo and proprietary programs.
Updated
On this page
- What a second reverse mortgage is
- A client who kept her rate
- The two options I priced
- Video: her two options
- Who qualifies for a reverse mortgage second
- Eligible properties and first liens for a reverse second
- How to tell which one fits
- Reverse second vs FHA HECM
- Pros & cons of HECM vs reverse second
- HELOC vs reverse second
- What this loan is also called
- Non-borrowing spouses
- Reverse mortgage calculator
- Reverse second authoritative sources
- FAQ reverse mortgage second
- Where to start on a reverse mortgage second
What a second reverse mortgage actually is
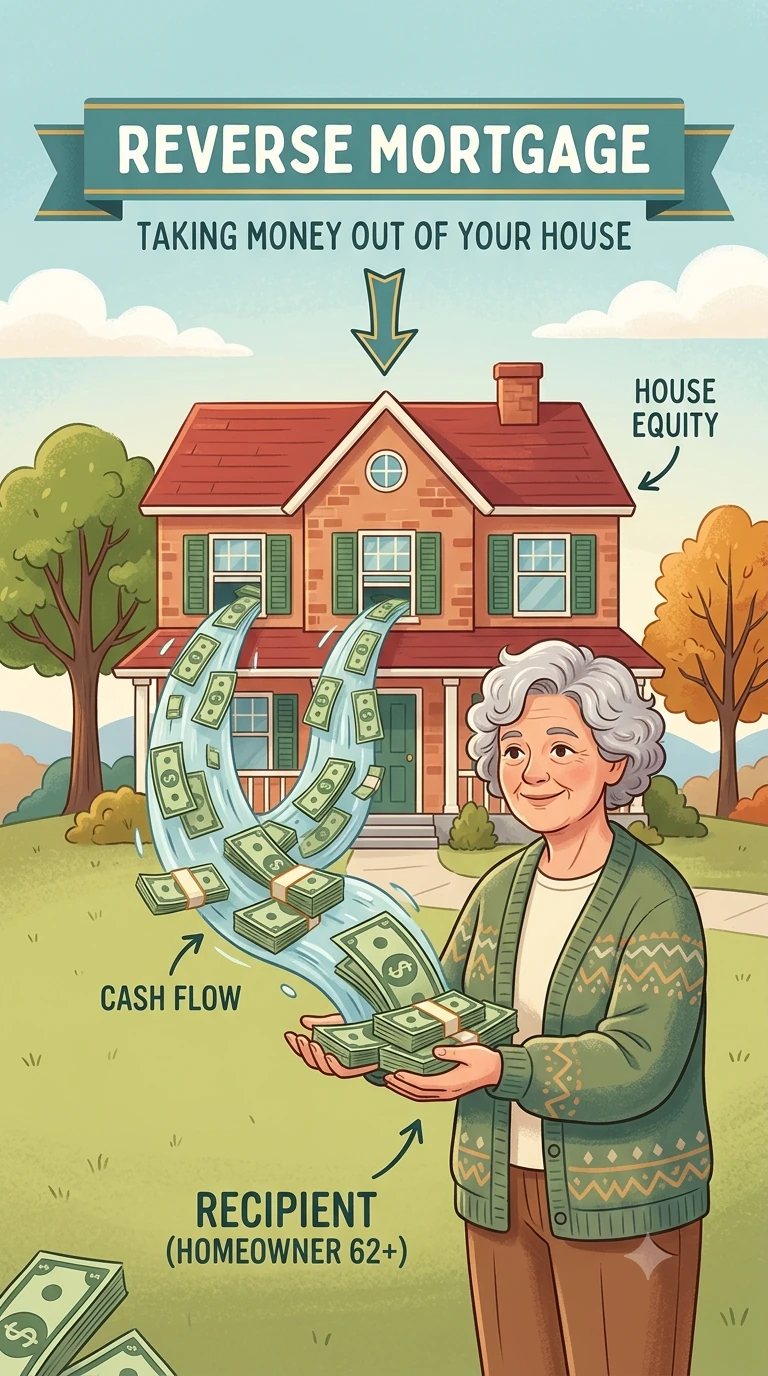
A standard reverse mortgage has to be in first position. If you still owe money on your house, the reverse mortgage pays that balance off at closing out of your proceeds. For a lot of borrowers that is the whole point, because the monthly payment goes away with it.
But it means your old loan is gone, and whatever you owed on it is now sitting inside a reverse mortgage balance that grows.
A second reverse mortgage skips that step. Your first mortgage stays exactly where it is. The reverse loan goes behind it in second position, you take your money as a one-time lump sum, and no payment is required on it. You keep paying the first mortgage, and you keep paying property taxes, homeowners insurance and upkeep, the same as with any reverse mortgage.
The program I place is called the HomeSafe Second, from Finance of America. It runs from $50,000 to $1,000,000, so it is not built for small needs, and you still complete reverse mortgage counseling with an independent counselor. The property rules and the rules about your existing mortgage are stricter than most people expect, and they are further down this page.
A client who kept her rate
I quoted a woman recently who had a mortgage rate she is never going to see again. She got it during the years when money was cheap, she has been paying on it ever since, and the idea of handing it back bothered her more than anything else about the conversation.
She was not being sentimental. A cheap mortgage that is steadily paying itself down is a real asset, and giving one up to take a reverse mortgage at today’s pricing is a genuine cost. Most people in her position feel this, and most of them are right to.
So she asked the obvious question. Is there a way to get money out of the house without touching the loan I already have?
There is. That is exactly what a second reverse mortgage does.
So I priced it for her. Then I priced the government-insured option next to it, because she deserved to see both before she picked one.
The two options I priced for her
She had two of them, and they solved different problems.
The second reverse mortgage. Her mortgage stays exactly where it is. She keeps the rate she likes, she keeps making the same payment she has been making, and she takes her money as a lump sum. In her case it also produced more cash than the other option did, which surprised her.
The FHA-insured HECM. This one pays her mortgage off, so the low rate goes away and so does the monthly payment. In exchange it carries a lower interest rate of its own, and instead of a lump sum it sets up a line of credit. She draws what she needs when she needs it, and she is not paying interest on money she has not touched.
Neither of those is a trap. They are two different answers to two different questions.
Watch: the two options I showed her
Who qualifies for a second reverse mortgage*
Credit drives which of two review paths your file takes, and the lighter path skips income documentation entirely.
| Credit score | Review path | What that means |
|---|---|---|
| 720 and above | Simplified assessment | No income documentation. You sign a certification that you have sufficient resources to meet your obligations |
| 600 to 719 | Full assessment | All income types are allowed, and residual income has to be met |
| Below 600 | Not eligible | This is a hard floor, not a pricing adjustment |
Both paths look at the same history. Twenty-four months of property tax payments, HOA or condo dues current at closing with no lien or notice of default, and twelve months of continuous hazard and flood coverage with no lapse.
Where they split is your mortgage record. The simplified path wants 24 months with no 30-day lates, no forbearance or deferment in that window, and at least five years left on your first mortgage term. The full assessment wants a clean 12 months, and allows up to two 30-day lates in months 13 through 24.
What property, and what first mortgage*
Two separate gates, and people usually clear one and trip the other.
Properties that work for a second reverse mortgage
- Single-family homes
- Planned unit developments
- Condominiums and townhomes, where the project meets the lender’s approval rules
- Two to four unit properties, with you living in one of them
Manufactured and modular homes do not qualify, and there is no workaround on that one.
First mortgages that disqualify you
The loan you already have has to be a normal amortizing mortgage in good standing. These rule you out:
- Interest-only
- A balloon payment due at maturity
- Negatively amortizing
- A private lender loan
- A rehab loan still in its construction or draw period
- A Texas 50(a)(6) loan
- Any reverse mortgage, including a HECM. You cannot stack two of these
A HELOC in first position is the common edge case. It works only once it has moved into the repayment phase.
How to tell whether a second reverse mortgage fits
More money and keep your rate, or a lower rate and only borrow what you need. That is the trade.
A few things push the decision one way or the other.
How much do you need, compared to what you still owe?
This matters more than most people expect. The government loan has to pay off your existing mortgage before it hands you anything, and it carries an insurance premium on top. When you only need a modest amount, that overhead is heavy, and keeping your mortgage and borrowing behind it often comes out better. When you need a large amount, second-position money is priced higher and that difference adds up over fifteen or twenty years.
Do you want the money now, or over time?
A lump sum is money you have. A line of credit is money you can get. If you know exactly what you need it for, the lump sum is simpler. If you are building a cushion for the next decade, the line of credit usually serves you better, and the unused portion grows.
How much does the payment matter?
With the HomeSafe Second you keep writing that check every month. Some people want it gone. Others look at the rate they have and decide it is the cheapest money they will ever borrow, and they would rather keep paying it.
There is no universal right answer here. There is a right answer for your situation, and it takes about twenty minutes to find it. If you are still deciding whether any reverse mortgage belongs in the picture, start with is a reverse mortgage right for me.
Second reverse mortgage vs the FHA HECM*
These are the two loans I price against each other most often, and they are built on opposite assumptions. One keeps the mortgage you have. The other replaces it.
| Second reverse mortgage | FHA-insured HECM | |
|---|---|---|
| Lien position | Second, behind the mortgage you already have | First |
| Your existing mortgage | Stays in place. Same rate, same payment | Paid off at closing, and the payment goes with it |
| Minimum age | Age 55, age 60 in Washington, age 62 in Texas | Age 62 |
| How the money reaches you | One lump sum at closing | Lump sum, line of credit, monthly term or tenure payments, or a mix |
| Rate type | Fixed | Fixed or adjustable |
| Payment required on the reverse loan | None. You can pay toward it any time without penalty | None |
| Line of credit that grows | No | Yes, on the adjustable version |
| FHA mortgage insurance | None | Yes, upfront and annual |
| Non-recourse | Yes | Yes |
| Amount | $50,000 to $1,000,000 | Counts home value up to the federal limit, $1,249,125 in 2026 |
| Counseling | Required | Required on every HECM, in every state |
| Non-borrowing spouse protection | Set by the loan agreement, not federal rule | Federal, under 24 CFR 206.55 |
Second reverse mortgage pros and cons vs a HECM
Measured against the government-insured loan, not against doing nothing.
Where it wins
- You keep the first mortgage you already have, rate and payment unchanged.
- No FHA mortgage insurance, upfront or annual.
- It starts at age 55 in most states instead of age 62.
- When you owe enough that a HECM would spend most of its proceeds on the payoff, this often puts more cash in your hands.
- No payment is required, and you can pay toward the balance any time without a penalty.
- Proceeds are generally not treated as income and are generally not taxable. Confirm your own situation with a tax advisor.
- You keep title to the home.
Where it costs you
- The balance grows, because you are not paying the interest down.
- Second-position money is priced higher than a HECM, and that gap compounds over fifteen or twenty years.
- You still write the first mortgage payment every month.
- One lump sum, so there is no line of credit building in the background.
- Upfront costs typically run higher than a traditional mortgage, a HELOC, or a home equity loan.
- It only works if you already have a qualifying first mortgage in place.
- Needs-based benefits such as Medicaid and SSI can be affected. Social Security and Medicare generally are not.
- It is not FHA-insured, so a non-borrowing spouse has whatever the loan agreement gives them.
Second reverse mortgage vs a HELOC
Both of these leave your first mortgage alone, which is why people line them up against each other. The difference is what each one asks of you afterward.
A HELOC expects to be paid back. You draw on it and a payment is due every month, the rate moves, and the payment moves with it. A HELOC is also a line rather than a closed loan, which means the lender can reduce it or freeze it. That has happened to a lot of homeowners at exactly the moment they needed the money.
A second reverse mortgage asks for no payment at all. Nothing is due on it while you live in the home. The money funds once, at closing, and it is yours. Nobody can freeze it later, because there is nothing left to freeze.
Qualifying is different too. A HELOC is underwritten on your income and credit the way any new monthly obligation is. A reverse mortgage still looks at your finances, but it is not asking whether you can carry a new payment, because there is no new payment to carry.
The tradeoff is real, and it runs the other way. A HELOC lets you borrow a little, pay it back, and borrow again. A second reverse mortgage is drawn once, and the balance grows over time because you are not paying the interest down. If you want a small amount for a short stretch and you can comfortably carry a second payment, a HELOC is often the cheaper tool. If you want money without adding a payment, or you want certainty that the money cannot be pulled back, that is what this is for.
There is a third way people reach equity without selling, a home equity investment, where an investor buys a share of your future appreciation instead of lending you money. It is a different animal and worth understanding before you rule it in or out.
If you are weighing a HELOC against a standard first-position reverse mortgage instead, where the reverse loan would pay your mortgage off, that comparison is here: reverse mortgage vs a HELOC.
What you might see this loan called
The naming is inconsistent across the industry, and it throws people off. A second reverse mortgage, a 2nd reverse mortgage, and a reverse second mortgage all describe the same structure: a reverse loan recorded behind the first mortgage you already have.
Lenders then put their own name on top of that. The one I place is the HomeSafe Second reverse mortgage from Finance of America, written in some places as the HomeSafe Second mortgage. It sits inside their broader HomeSafe mortgage line, alongside the first-position jumbo program. If you searched any of those phrases and landed here, you are in the right place.
* About these terms. Program terms and eligibility shown on this page come from the lender’s published guidelines. They vary by lender and by state, and they change without notice. Nothing here is a commitment to lend or an offer of credit. What you actually qualify for is set by the guidelines in effect when you apply, and depends on a complete application, credit and property review, counseling, and an appraisal. Get preapproved before you plan around any of it, and call me and I will tell you what is current.
If you are married and only one of you is on the loan
This deserves its own conversation, and it is the part I see handled worst.
With a HECM, the protection for a spouse who is not on the loan is federal. It is written into the rules, it has clear conditions, and an eligible non-borrowing spouse can stay in the home after the borrower dies.
Proprietary products like HomeSafe are not FHA-insured and are not governed by those rules. Finance of America says so directly in their own materials: each lender sets its own policy, and the only reliable way to know your rights is to read the loan agreement.
There is a second wrinkle people miss. With a HomeSafe Second there are two loans on the house, so the question has to be answered twice. The reverse loan is one piece. The first mortgage is the other, and a surviving spouse who keeps the house also keeps that payment, usually on less income than the household had before.
If there is a spouse who will not be on the loan, bring it up early. It can change the answer.
Reverse Mortgage Calculator
Let’s see what your equity can do without touching your first mortgage.
A reverse mortgage is a loan. The balance grows over time and is repaid when the last borrower leaves the home. You keep the title, and you remain responsible for property taxes, homeowners insurance, and upkeep.
- 1Property
- 2Value
- 3About You
- 4Your Estimate
This form collects information so Christopher Gibson can prepare a personalized estimate. It does not generate a quote, an approval, or an offer of credit, and nothing here is a commitment to lend. Final terms depend on a complete application, underwriting review, a HUD-approved appraisal, and the rates in effect at the time of lock. HUD requires independent counseling before any HECM closes. Your information is secure and never sold. Christopher Gibson, NMLS #1910430. Equal Housing Opportunity. Privacy Policy.
Authoritative sources
From the source: HUD’s HECM program for how the government-insured side works, the Consumer Financial Protection Bureau on reverse mortgages generally, and reversemortgage.org from NRMLA. Non-borrowing spouse protection on an FHA loan is set out at 24 CFR 206.55. For more, see the plain-English reverse mortgage guide, the requirements, the types of reverse mortgages, and the resource library.
Frequently asked questions
These are the ones specific to a second reverse mortgage. The full reverse mortgage FAQ covers the rest.
Can you get a second reverse mortgage if you already have one?
No. You cannot have two reverse mortgages on the same property. A second reverse mortgage means a reverse loan in second lien position behind a conventional first mortgage, not a second reverse loan stacked on an existing one.
Do I still make a payment on a second reverse mortgage?
On the first mortgage, yes. On the second reverse mortgage, no — you can pay as much or as little toward it as you want, including nothing. You are also still responsible for property taxes, homeowners insurance, and keeping the home up, the same as with any reverse mortgage.
Can I take the money a little at a time?
No. It is a lump sum, taken at closing. If you want money you can draw on over time instead, that is what the HECM line of credit is for, and it is worth pricing both.
How old do I have to be?
Age 55 in most states where it is offered, age 60 in Washington, and age 62 in Texas. Those are ages, not years of ownership.
What if I owe too much on my house?
Then this may be your only reverse mortgage option, because a HECM would have to pay that balance off first and might not leave you anything.
Is a second reverse mortgage the same as a HELOC?
No. A HELOC requires monthly payments, the rate moves, and the lender can freeze the line. A second reverse mortgage requires no payment, and the money is yours once it funds.
What happens at the end of a HomeSafe Second loan, when I pass away or move out?
Both loans become due. Your heirs can sell the home, refinance, or pay the balances off. These are non-recourse loans, so if the home sells for less than what is owed, your heirs are not responsible for the shortfall. If it sells for more, the difference is theirs.
Which states can I get one in?
I am licensed in Washington, Colorado, Texas, Florida and Michigan, and program availability varies by state. Call and I will tell you in about a minute whether it is available where your home is.
Free guide: Your Home Can Help
My complete guide to reverse mortgages: the retirement squeeze, the myths, your options, real client stories, and what it really costs. Pick the state your home is in. No email required.
Where to start
If you have a mortgage you do not want to lose and you need money out of your house, this is worth twenty minutes of your time. The thing to bring to that conversation is not your rate. It is a real number for what you need, and a recent statement showing what you still owe. Those two figures tell us most of what we need to know. You can also request a quote and I will come back to you with numbers.
Rates and loan limits move, so I am not going to print numbers here that will be wrong by the time you read them. Call and I will run yours.
About Christopher Gibson
I am Christopher Gibson, a mortgage broker and reverse mortgage specialist with C2 Financial (NMLS #1910430), licensed across Washington, Colorado, Texas, Florida, and Michigan. I spend my days matching homeowners age 55 and older to the right loan, and telling them when none of them fit. Call or text 720-449-6622 and we will find out whether keeping your first mortgage is the right move, same day, with no credit pull to get a ballpark.